
Beyond the Traditional Home Loan: Understanding Real Estate Financing Options
Real estate financing isn't limited to purchasing a primary residence. Investment properties, second homes, land and other real estate opportunities can involve different financing considerations. Understanding those differences is an important first step.
By Sandy Biondo | Consolidated Lenders Group

When most people hear the word “mortgage,” they picture one thing:
Buying a home to live in.
But real estate financing can extend well beyond a traditional primary-residence purchase.
You may be considering an investment property, a second home, land, or another type of real estate opportunity. Each situation can come with its own financing considerations, qualification requirements and questions.
With decades of mortgage and real estate financing experience, I've worked with clients whose needs don't always fit neatly into one box.
The first step isn't choosing a loan.
It's understanding what you're trying to accomplish.
Not Every Property Is Financed the Same Way
The type of property you're purchasing—and how you intend to use it—can affect the financing options that may be available.
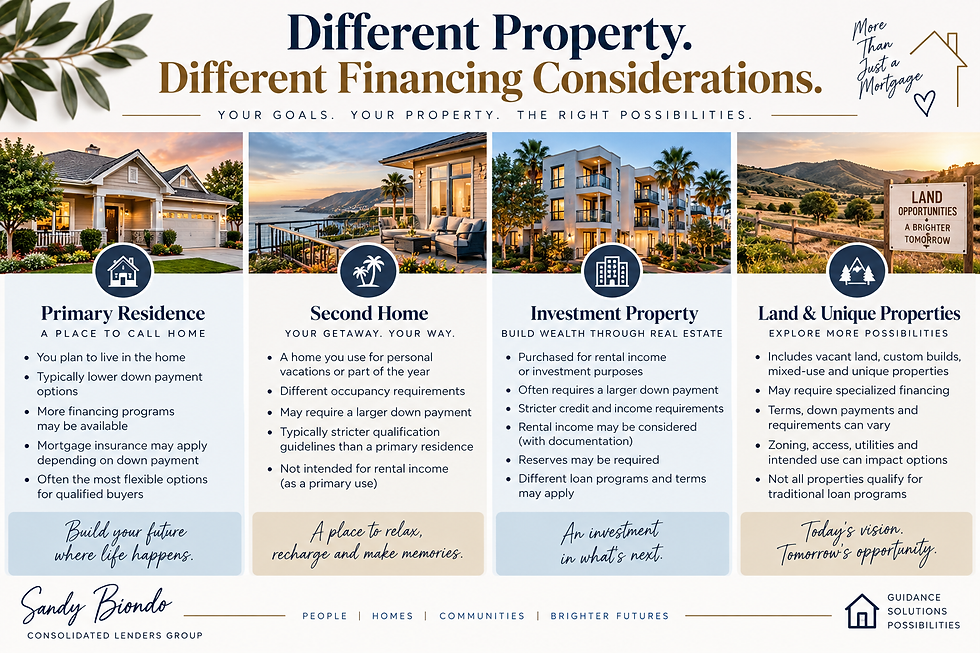
A lender may look differently at a home you'll occupy as your primary residence than at a property you're purchasing as an investment.
Other factors can include:
Property type
Intended occupancy
Income and assets
Credit history
Existing financial obligations
Down payment or available equity
Property value and condition
The type and purpose of the financing
That's why it's important to discuss the property and your goals before assuming a particular loan will be the right fit.
1. Investment Property Financing
Real estate can be purchased for investment purposes rather than as a primary home.
For example, someone may be considering a:
Single-family rental • Condominium • Multi-unit property • Other residential investment property
Financing an investment property may differ from financing a primary residence.
Depending on the loan and circumstances, lenders may have different requirements involving down payment, reserves, credit, qualifying income and other factors.
Potential rental income may also be considered in certain circumstances, subject to applicable guidelines and documentation requirements.
If you're considering an investment property, it's helpful to understand the financing before evaluating whether a particular opportunity makes sense for you.
2. Financing a Second Home
Maybe you're considering a vacation property, a place closer to family or another home you plan to use personally.
A second home isn't necessarily financed the same way as either a primary residence or an investment property.
Occupancy and property-use requirements can matter, and simply calling a property a “second home” doesn't automatically make it eligible for second-home financing.
Understanding how the property will actually be used is an important part of determining which financing options may apply.
3. Multi-Unit Properties
Properties containing more than one residential unit can introduce additional considerations.
Depending on the property and financing, an owner may plan to:
Live in one unit and rent another
or
Purchase the property entirely as an investment.
Those two situations aren't necessarily treated the same way.
The number of units, intended occupancy, rental income and other property characteristics can all affect financing.
For someone interested in real estate investing, a multi-unit property may be worth exploring - but it's important to understand both the financing requirements and the responsibilities that come with owning rental property.
4. Land and Unique Properties
Not every real estate purchase involves a conventional move-in-ready house.
Some buyers may be considering:
Vacant land • Properties with unusual characteristics • Certain mixed-use properties • Other nontraditional real estate
These properties can require different financing approaches.
Factors such as property use, zoning, improvements, access, utilities, condition and intended plans may affect which financing sources are willing to consider the property.
This is one area where discussing the transaction early can be particularly helpful.

5. Using Equity for Real Estate Goals
Some property owners may also consider whether equity in real estate they already own could play a role in their future plans.
Depending on individual circumstances and available financing, options involving home equity may provide access to funds.
But borrowing against equity also creates additional debt secured by the property.
Before making that decision, it's important to understand things such as:
The new payment
Interest and financing costs
Available equity
Qualification requirements
How the borrowed funds will be used
The potential effect on your overall financial position
Having equity doesn't automatically mean borrowing against it is the right decision.
Start With the Purpose, Not the Product
One of the easiest mistakes to make is starting with:
“Which loan should I get?”
I'd rather start with:
“What are you trying to accomplish?”
Are you purchasing your first investment property?
Looking for a second home?
Considering a multi-unit property?
Exploring land?
Trying to understand whether your existing real estate can help you reach another goal?
Once the objective is clear, it's much easier to begin exploring financing that may fit the situation.
Real Estate Financing Is About the Whole Picture
The interest rate matters—but it isn't the only consideration.
Depending on the transaction, you'll also want to understand:
Down payment and cash requirements
Monthly payment
Loan term
Closing costs
Reserve requirements, when applicable
Property and occupancy requirements
Potential mortgage insurance, when applicable
Prepayment terms or other loan features, when applicable
And, most importantly, whether the financing makes sense for what you're trying to accomplish.
Experience Matters When the Situation Is Different
Real estate financing isn't always one-size-fits-all.
With decades of mortgage and real estate financing experience, my approach is to first understand your property, circumstances and goals.
From there, I can help you explore available financing possibilities, understand important differences and ask the right questions before you make a decision.
Sometimes the best place to begin isn't an application. It's a conversation.
Have a Real Estate Financing Question?
Whether you're considering an investment property, second home, multi-unit property, land or another real estate opportunity, Sandy can help you explore the financing side of your plans.
Tell Sandy what you're trying to accomplish, and start from there.

Disclaimer
This information is provided for general educational and informational purposes only and is not intended as financial, legal, tax, or investment advice. Every borrower's situation is different. Loan programs, rates, terms, eligibility requirements, property requirements, and costs are subject to change and may vary based on individual circumstances. All loans are subject to applicable underwriting and approval requirements. Borrowing against home equity creates debt secured by your property and may increase your total borrowing costs. Refinancing may increase the total finance charge over the life of the loan. This information is not a commitment to lend or a guarantee of loan approval. Please contact Sandy Biondo at Consolidated Lenders Group, Inc. to discuss your individual financing needs.


Comments